EPF Akaun Fleksibel: should you withdraw before the year-end rush? A kind, practical guide
Eternity Job Career Team18 November 2026 · 8 min read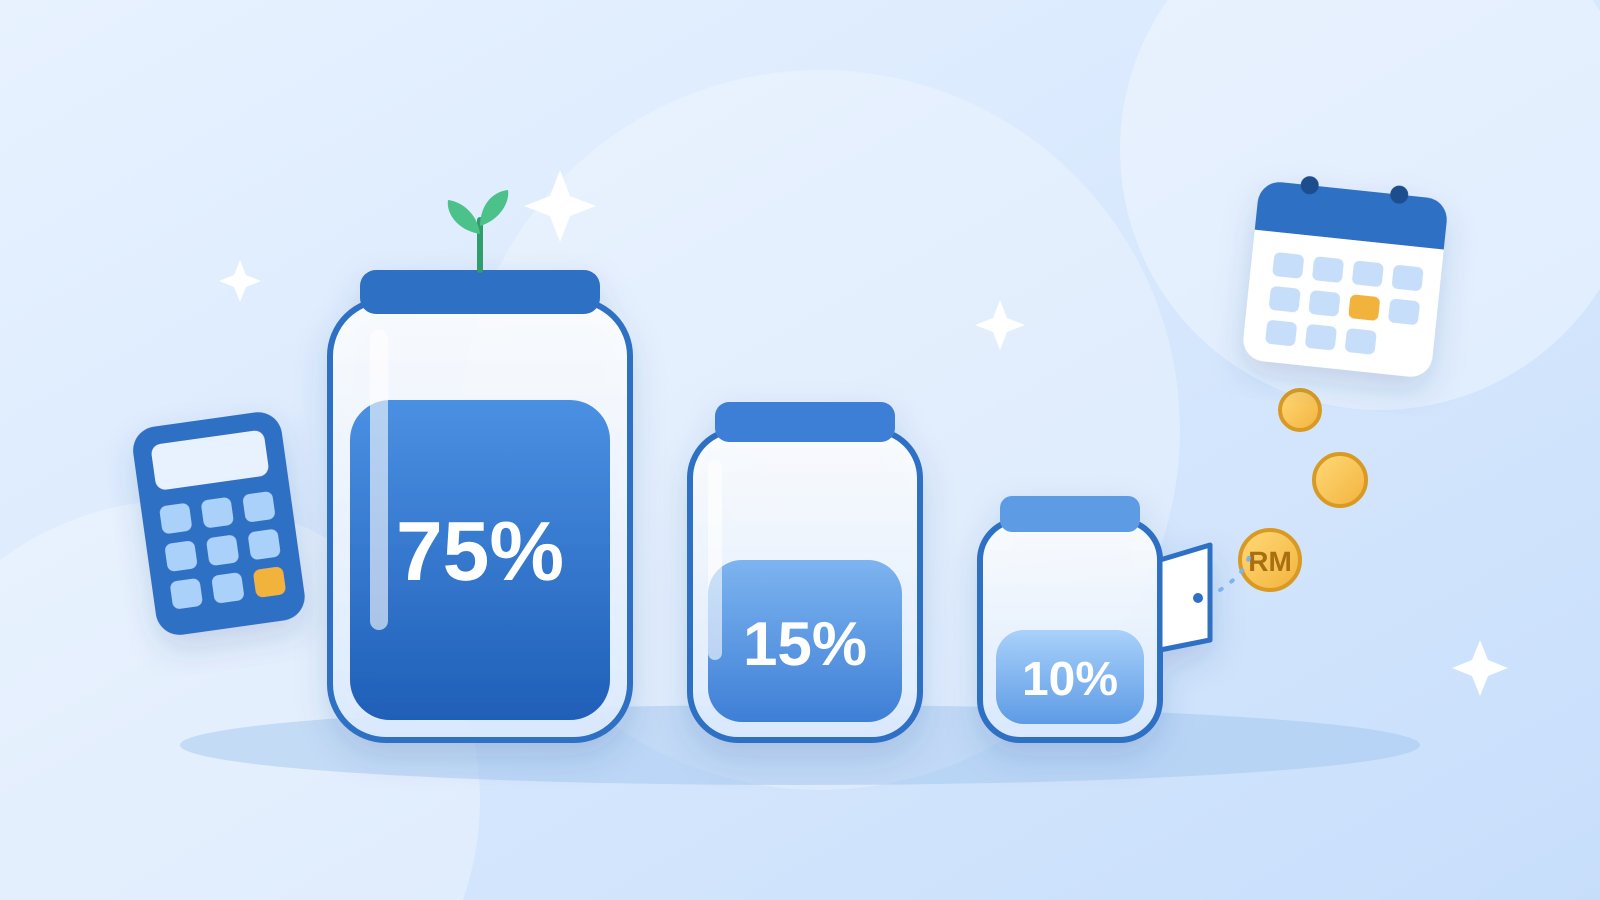
It's that time of year. Year-end sales, a family trip, Chinese New Year just around the corner, and a list of school items for January that seems to grow every week. Then a friend says, "Eh, just take from your EPF Account 3 lah. It's your money."
They're right that it's your money. And it's completely okay to use it when you need it. This guide walks you through how Akaun Fleksibel works in 2026, how to withdraw, and a gentle way to decide whether now is the right time.
What's inside
Your three EPF accounts, in plain words
How Akaun Fleksibel withdrawals work
How to apply, step by step
What other Malaysians are doing
The quiet cost of withdrawing
Good reasons to withdraw, and reasons to pause
If you decide to leave it alone
Your quick checklist
Your three EPF accounts, in plain words
Since 11 May 2024, the EPF (KWSP) has split the monthly contributions of members below 55 into three accounts:
Account | Share of new contributions | What it's for |
|---|---|---|
Akaun Persaraan (Retirement Account, formerly Account 1) | 75% | Your retirement. Generally locked until 55. |
Akaun Sejahtera (Wellbeing Account, formerly Account 2) | 15% | Specific needs such as housing, education, health and Hajj, each with its own rules. |
Akaun Fleksibel (Flexible Account, often called "Account 3") | 10% | Withdraw any time, for any reason. |
So if you and your employer contribute RM1,000 in total in a month, about RM100 lands in Akaun Fleksibel.
When you turn 55, the savings in all three accounts are combined into Akaun 55, and the Akaun Fleksibel withdrawal no longer applies.
How Akaun Fleksibel withdrawals work
Here are the basics, based on the EPF's own Akaun Fleksibel withdrawal page:
Who can withdraw: Malaysian and non-Malaysian members below 55 who have savings in Akaun Fleksibel.
Minimum amount: RM50 per withdrawal. If your balance is below RM50, you'll need to wait until it builds up.
Reason needed? No. You don't need to explain why or provide supporting documents.
Where the money goes: Straight to an active savings or current account in your own name (not a joint or company account).
How long it takes: The EPF says payment is made within seven working days after your application is approved. In practice, many people receive it sooner.
Bigger amounts: You may be asked to verify your identity, for example by eKYC in the app or a thumbprint at an EPF Self-Service Terminal, especially for a first withdrawal or if your bank details have changed.
No take-backs: Once approved, an application can't be cancelled, so decide calmly first.
Does it still earn dividends? Yes. Whatever stays in Akaun Fleksibel earns the same dividend rate as your other accounts, and dividends are credited to each account based on its own balance. For 2025, the EPF declared 6.15% for both conventional and Shariah savings. If you withdraw everything, that account simply earns nothing until it fills up again.
How to apply, step by step
Open the KWSP i-Akaun app (or the i-Akaun member web portal) and log in.
Check your Akaun Fleksibel balance so you know what's available.
Choose the Akaun Fleksibel withdrawal and key in the amount (RM50 or more).
Confirm your bank account is correct and in your own name.
Complete identity verification if the app asks for it.
Submit, then watch for the confirmation in the app.
Prefer to do it in person? You can also apply at any EPF office, and the EPF says no form is needed for this one.
A gentle safety note: apply only through the official i-Akaun app, the official portal or an EPF office. Please don't share your i-Akaun password or verification codes with anyone who offers to "help you withdraw faster", even if they sound friendly and official.
What other Malaysians are doing
You're not alone in thinking about this. A few numbers help put it in perspective:
An EPF research report published in April 2026 found that about 63% of eligible members (8.4 million people) had not withdrawn from Akaun Fleksibel between May 2024 and October 2025. Many of them, though, simply had a balance too small to withdraw.
The same report found that most withdrawals went to everyday essentials, such as daily necessities, health costs and emergencies.
In a written reply to Parliament, the Ministry of Finance said members had withdrawn about RM19.87 billion from Akaun Fleksibel as of 31 May 2026, involving about 5.5 million members.
In other words, many people are using this account exactly as it was designed: as a cushion for real needs. There's no shame in that.
The quiet cost of withdrawing
The money you take out today stops growing for you. Here's a simple illustration (not a forecast, since EPF dividends change every year):
RM1,000 left to grow at 5% a year would become about RM1,629 in 10 years and about RM2,653 in 20 years.
That's the trade-off the EPF itself has highlighted: Akaun Fleksibel gives relief now, but regular withdrawals for everyday spending can slowly shrink what's there for you later. It doesn't mean "never withdraw". It just means it's worth a short pause before you tap the button.
Good reasons to withdraw, and reasons to pause
It can make sense to withdraw when:
It's a real emergency, such as a medical bill, an urgent car or home repair, or a sudden loss of income, and you don't have other savings to cover it.
It helps you avoid expensive debt. Credit card interest in Malaysia can be up to 18% a year under Bank Negara Malaysia's tiered pricing. Using Akaun Fleksibel to stop a balance from snowballing can be kinder to your future than paying that interest.
It covers an essential, planned cost, like school fees or uniforms, that you couldn't fully save for this year.
It may be worth pausing when:
It's for a "nice to have", such as a sale, a new phone or a holiday, that could wait a few months.
You'd be withdrawing small amounts every month just to get by. That's a sign it may help to look at your budget, or talk to someone, rather than draining the account bit by bit.
You haven't checked other options, such as an annual bonus, a festive allowance, or simply waiting until after payday.
A kind three-question check before you withdraw:
Is this a need, or a want I could plan for?
What happens if I wait one month?
Am I withdrawing only what I need, not the whole balance?
If money feels tight for a while, you don't have to figure it out alone. The AKPK (Agensi Kaunseling dan Pengurusan Kredit) offers free financial counselling and debt management help, and the EPF's Belanjawanku guide gives realistic monthly budget figures for Malaysian households.
If you decide to leave it alone
That's a perfectly good choice too. Your Akaun Fleksibel savings keep earning dividends, and the money stays available any time you truly need it. Think of it as a ready-made emergency fund that's working quietly in the background.
If you'd rather your savings stayed focused on retirement, the EPF has said members can move savings out of Akaun Fleksibel into their other accounts. Ask at an EPF office or check the i-Akaun app for the current process before you decide, because moves like this generally can't be reversed.
Your quick checklist
[ ] I've checked my Akaun Fleksibel balance in the KWSP i-Akaun app
[ ] I know the minimum withdrawal is RM50
[ ] I've asked myself: need or want? What if I wait a month?
[ ] I'm withdrawing only the amount I really need
[ ] My bank account is active and in my own name
[ ] I'm applying only through the official app, portal or an EPF office
[ ] I understand an approved application can't be cancelled
The bottom line
Akaun Fleksibel is there to help you, and using it for a real need is nothing to feel guilty about. The trick is to use it on purpose rather than on impulse. Take a breath, ask yourself a couple of simple questions, and withdraw only what you need. Your future self will thank you for the pause, whichever way you decide.
Planning ahead for 2027? See our guides to your annual bonus and increment, reading your payslip line by line and what Budget 2027 means for your salary and tax. And if a better-paying role would ease the pressure, browse jobs on Eternity Job.
This guide is general information, not financial advice. EPF rules can change, so please check the latest details on the official KWSP website or i-Akaun app before you apply.